All Categories
Featured
Navigating the Next Middle East Business Environment
Table of Contents
To reverse a years of deteriorating overall factor efficiency, regional labour market policy is moving from easy task production to managing active labor force shifts. Federal governments and companies are scaling short, modular training programmes and micro-credentials in data analytics and digital operations to gear up workers for emerging functions. Workplace-based learning and apprenticeship-style paths are becoming more common as firms incorporate AI tools into daily workflows.
With oil rates anticipated to average $55-60 per barrel in 2026, regional governments are intensifying their focus on expense discipline and personal capital mobilisation. Fiscal policy is rotating toward the monetisation of state-owned properties in logistics, utilities, and desalination to redirect funds toward higher-impact financial investments. While borrowing by means of sukuk and sustainability-linked bonds is expected to increase to fund tactical deficits, the focus remains on enhancing non-oil earnings structures.
PwC Middle East financial policy and method partner Jing Teow stated: "Having currently mobilised capital and policy at scale, GCC federal governments are now focused on shipment. In 2026, the priority is strengthening financial strength through more protected trade and investment relationships, efficient AI release, handled labor force shifts and disciplined financial policy in a more tough and fragmented worldwide environment.".
Saudi Arabia and UAE are poised to lead the Gulf region's financial expansion in 2026, supported by strong private-sector performance, durable domestic need and restored investment momentum, according to the most current ICAEW Economic Insight Q4 2025 report, produced by Oxford Economics. The GCC is anticipated to outshine most international regions peers next year, with local GDP projection to grow by 4.4%. Across the GCC, non-energy activity is forecasted to broaden by 4.1% in 2026, driven by strong labour markets, enhancing credit conditions and rising financial investment in technology and AI-related infrastructure.
Although oil incomes will be under pressure in the very first half of 2026, production is expected to rise again in the second half of 2026, supporting the region's medium-term outlook, it specified. Saudi Arabia will remain a significant factor to GCC momentum, with GDP forecast to grow 4.3% in 2026.
Operational Excellence: a Strategic Driver for 2026 Growth
Development will be supported by industrial growth and policy reforms, consisting of reduced foreign ownership guidelines that aim to stimulate additional investment. The financial deficit is projected to widen to 5.6% of GDP next year amidst softer oil rates, while the recent five-year rent freeze in Riyadh intends to reduce inflationary pressures, though it may constrain future real estate supply.
Strong domestic fundamentalsThe UAE is likewise positioned for another strong year of performance, with GDP forecast to rise 5.6% in 2026 as non-oil sectors continue to expand. Tourist, trade and financial services stay essential development motorists, supported by population development and sustained domestic demand. Dubai's economy grew 4.4% in the first half of 2025, reflecting broad-based non-oil strength.
Oil production is anticipated to get once again in the 2nd half of 2026, matching continuous investment in infrastructure, technology and global trade collaborations. Hanadi Khalife, the Head of Middle East, ICAEW, said: "This quarter's outlook enhances how far the GCC has can be found in building diverse, resistant and worldwide competitive economies.
How to Secure a Leading Advantage in 2026Scott Livermore, ICAEW Economic Advisor, and Chief Economic Expert and Handling Director, Oxford Economics Middle East, said: "Saudi Arabia and the UAE are getting in 2026 with strong structures. Saudi non-oil activity is getting pace, supported by robust need and increasing financial investment, even as fiscal pressures increase.""The UAE continues to benefit from strong domestic basics, a sharp uplift in government costs and sustained diversity efforts.
Advanced Planning for GCC LeadershipAccelerating Regional Industrial Growth through Innovation
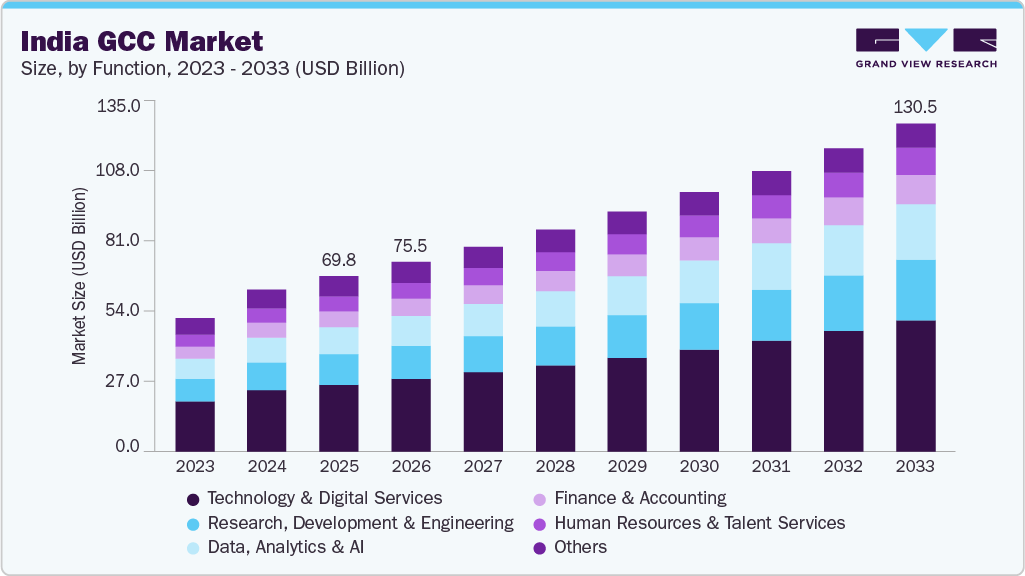
What differentiates 2026 from preceding years is not just the velocity of technological modification, though that acceleration is genuine, however rather a fundamental shift in how business develop of their GCCs' purpose. The is anticipated to grow to four hundred thirteen billion dollars by 2040, but this development masks a more extensive transformation.
Rather, they ask whether these centers drive innovation, own profit-and-loss obligation, and add to competitive differentiation. In 2026, the most successful GCCs will act like internal start-ups, nimble, cross-functional, insight-driven, and deeply aligned with global organization outcomes. This shift from execution to ownership represents perhaps the single most substantial tactical recalibration in the GCC model's advancement.
This week, we're assembling more than 3000 meetings between investors and 119 Gulf-listed business with a combined value of $2.4 trillion at the HSBC GCC Exchanges Conference 2026, in London. We're combining investors, companies, exchanges, and policymakers to discuss what is changing in the area, and what comes next, including the expansion and ongoing advancement of the Gulf's capital markets, and the region's growing function in global networks of capital and trade.

Latest Posts

Connecting Policy With Business Excellence Across the Gulf
Key Developments in the 2026 Middle East Market
How to Secure a Competitive Advantage in 2026